The difference between accounts receivable and accounts payable
October 22, 2026
-
0
min read
0
min read
Accounts receivable is money your customers owe you for work you've already invoiced. Accounts payable is money you owe your suppliers for what you've bought on credit. One is cash coming in, the other is cash going out, and both are waiting on a date in the future rather than sitting in your bank account. That's the whole difference, and for most people it's the whole answer. What's worth knowing beyond it is that the two sides don't give you the same options: money you're owed can be chased, charged interest on, or financed, while money you owe can usually only be renegotiated.
Accounts receivable is everything you've invoiced and are still waiting to be paid for. You'll see it shortened to AR. It's money you have a right to but haven't got, and it stops being a receivable the moment the customer pays.
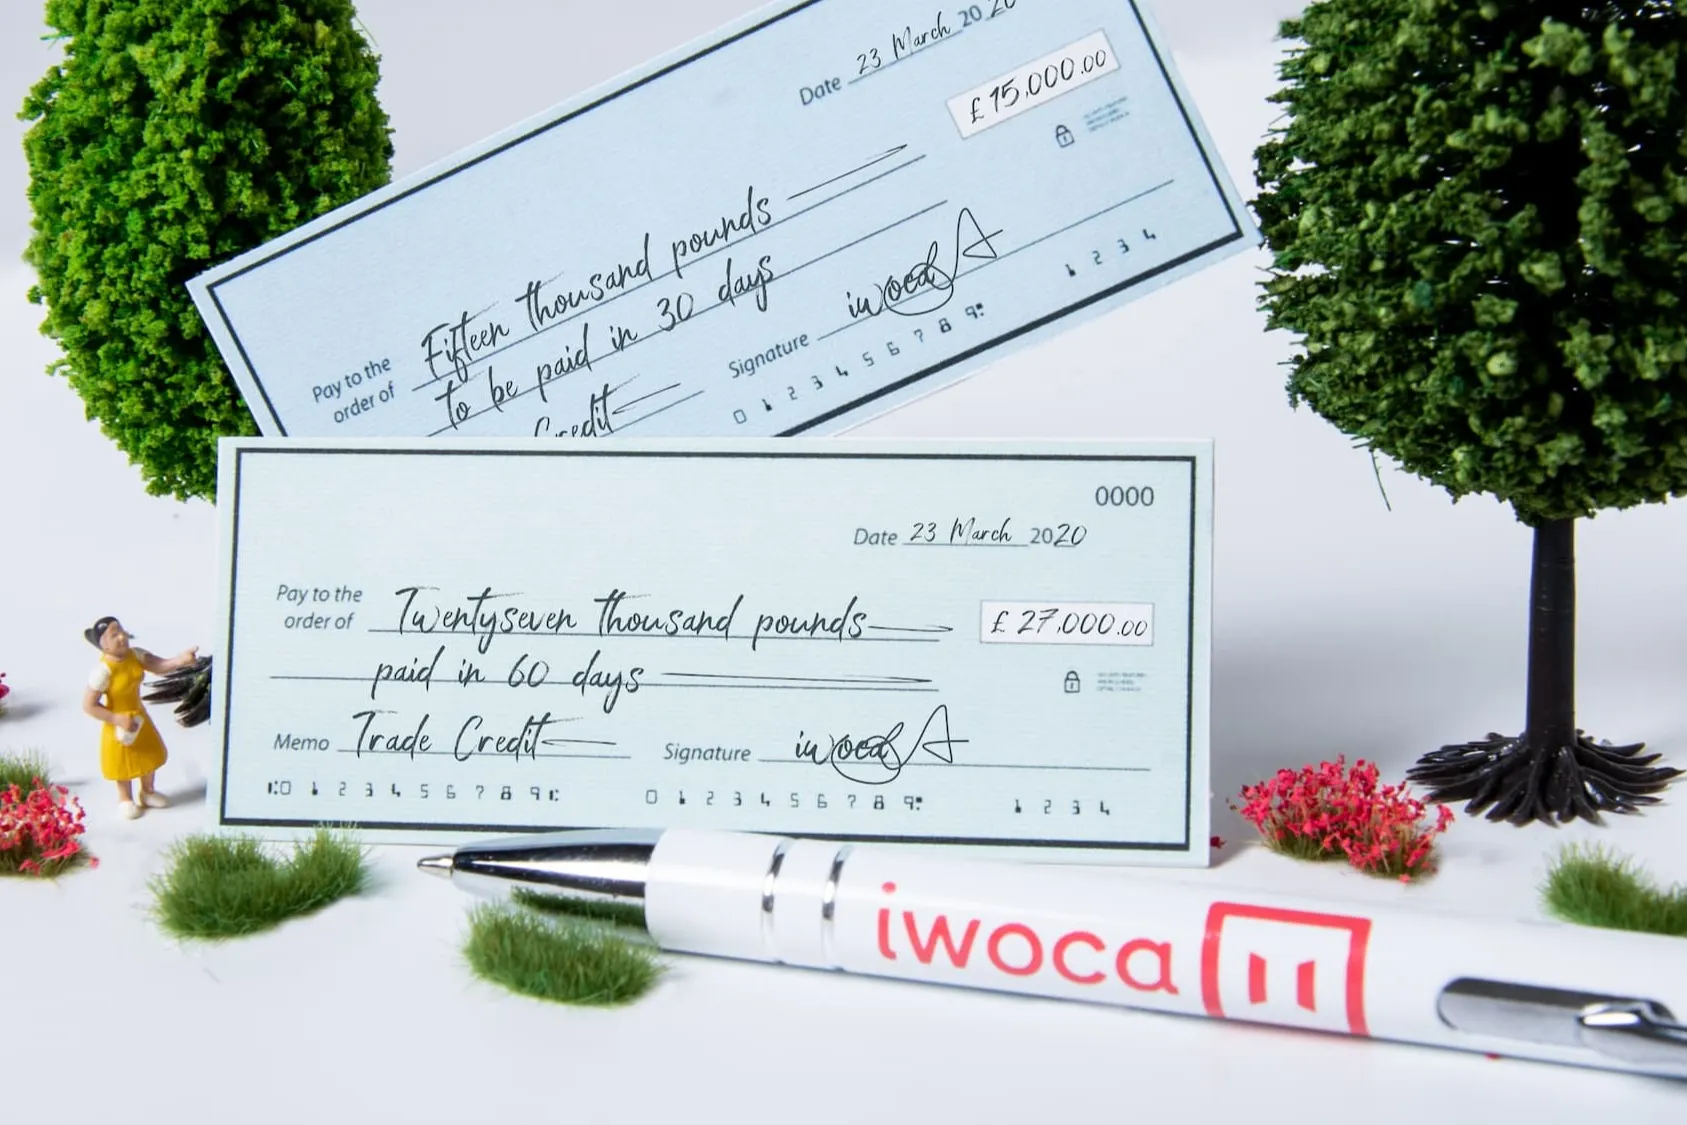
Your terms are whatever you agreed when the purchase order or contract was arranged. If you agree a payment date it has to be within 60 days for a business customer, or 30 days for a public authority, and you can agree longer with another business only if it's fair to both of you. If you never agreed a date, the law treats the payment as late 30 days after your customer gets the invoice or you deliver, whichever is later (late commercial payments on GOV.UK, checked on 14 October 2026).
The rest of the job is invoice, record, and follow up. You'd normally invoice once the goods or services have gone out, though plenty of work takes a deposit first, and the amount and terms sit in your sales ledger until the money arrives or someone chases it.
Accounts payable, or AP, is the other side of the same arrangement: the short-term bills you owe your trading partners. One starts the moment a supplier's invoice arrives for something you'd agreed to buy, and it ends when you pay it.
Almost anything you buy on credit can sit there – stock, materials, leasing, a business loan, your accountant's fee – while your employees' wages are handled separately. The 30-day default applies to you too, from the other side of the invoice.
Which is the simplest way to keep the two apart. A sales invoice you raise is your receivable and your customer's payable: one document, one amount, read from two sides. Whether an invoice is a receivable or a payable depends entirely on who issued it.
Receivables are money in and payables are money out. Everything else follows from that: one is an asset, the other is a liability, and your filed accounts call them something different again.
Those last two rows are the ones that trip people up. 'Trade debtors' and 'trade creditors' are the headings used in the statutory balance sheet formats, so they're the words you'll see in your own filed accounts and hear from your accountant (balance sheet formats on legislation.gov.uk). And a customer who owes you money is your debtor, not your creditor, which is worth having straight before any conversation about either.
A receivable and a payable of the same size look like mirror images on paper. They aren't, because they hand you completely different options when you're short of cash.
Money you're owed, you can chase, charge for, or finance. Once a commercial payment is late you have an automatic right to statutory interest of 8% over the Bank of England base rate, unless your contract sets a different rate (charging interest on commercial debt on GOV.UK). The base rate has been 3.75% since 18 December 2025, so statutory interest is 11.75% a year: on a £10,000 invoice that's £1,175 a year, or £3.22 a day, which is about £97 if your customer pays a month late. You can also charge a fixed sum for the cost of recovering it, once per payment – £40 up to £999.99, £70 from £1,000 to £9,999.99, and £100 at £10,000 or more (claim debt recovery costs on GOV.UK). Few small suppliers ever invoice the interest, and the point of knowing about it usually isn't the money. It's that you're negotiating from a stronger position than you thought. Past that there's chasing it properly, and financing what you're owed so the cash arrives now rather than in two months.
Money you owe, you mostly renegotiate. There's no equivalent lever on that side. You can ask for longer terms, agree a payment plan, or take an early-settlement discount where one is genuinely on offer, and all of it rests on the relationship rather than on a right you hold. What you can't do is quietly stretch it, because your supplier has the same claim over you that you have over your own late customers.
One rule does run in both directions, and it lands six months out. If a customer still hasn't paid six months after the due date and you've written the debt off in your VAT accounts, you can reclaim the VAT you already paid HMRC on that invoice. The same notice works the other way: if you reclaimed the VAT on a supplier's bill and still haven't paid it six months later, you have to pay that VAT back, and your supplier doesn't have to tell you (relief from VAT on bad debts on GOV.UK).
Profit and cash aren't the same thing, and the gap between your receivables and your payables is usually where the two part company. If your customers take 60 days and your suppliers want paying in 30, you're funding a month of trading out of your own pocket, and the faster you grow the bigger that month gets.
That gap is normal rather than a warning sign, but it's wider than most directors assume. Our research, published in April 2026, found that the average UK small business is owed more than £22,000, and that 90% of UK businesses are affected by late payments (five cash flow management tips). It bites hardest on companies with a handful of large customers, and on anyone whose own costs land before their invoices do: seasonal businesses, and anyone paying for labour or stock up front.
So the two ledgers are worth reading together, and worth reading monthly rather than at year end. The difference between your current assets and your current liabilities is your working capital, and movements in both ledgers are part of what turns a profit into operating cash flow, or fails to. Lenders and investors read those two numbers for the same reason you should.
Where the gap is a timing problem rather than a profit one, borrowing against might be a reasonable answer. If you're waiting on an invoice, a Flexi-Loan can cover the gap, and you can clear it with no early repayment fee once your customer pays – so it can be open for the three weeks between paying your suppliers and being paid yourself, rather than for a year.
iwoca is one of Europe's leading non-bank lenders. Since 2012, we've lent over £4.5 billion to 100,000 small and medium-sized businesses in the UK and Germany.
iwoca has won a number of awards, including Moneynet's best small business lender (2024) and best small business provider (2025). We've also been featured in major media outlets including The Independent, Forbes and the Financial Times.
Borrow £1,000 to £1 million to cover a gap, buy stock or take on your next order. Apply in five minutes and seee what you qualify for.
Borrow £1,000 to £1 million to cover a gap, buy stock or take on your next order. Apply in five minutes and seee what you qualify for.